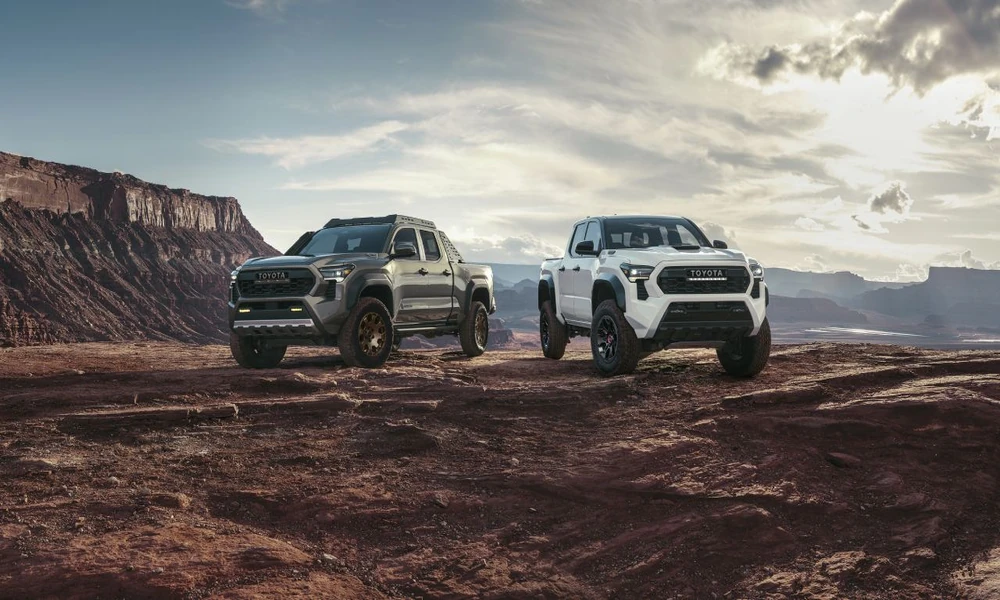
Tacoma Lease Versus Purchase, Comparing Monthly Costs at Space City Toyota, A Smart Guide for Houston Drivers
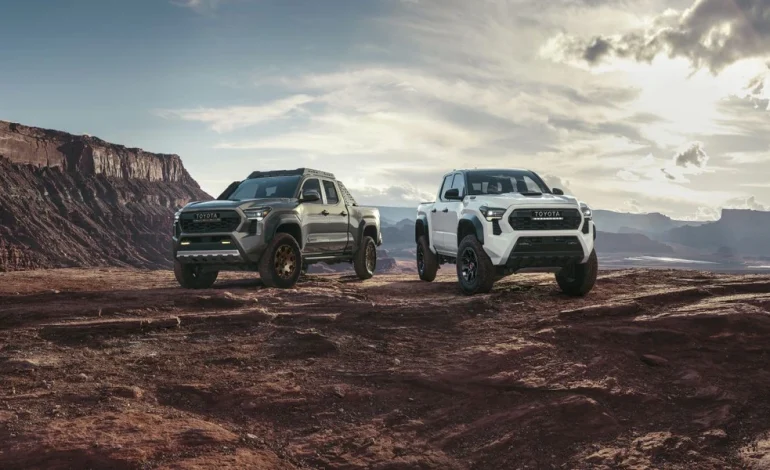

Choosing between leasing a pickup and owning one outright shapes your budget for years ahead. Shoppers who visit space city toyota often weigh both paths carefully before signing any paperwork. A leasing plan usually brings a smaller payment because you only cover expected depreciation. Financing a purchase costs more each month but builds equity you keep afterward. Knowing where every dollar goes helps you pick the route that truly fits your life.
Why Leasing Payments Usually Start Lower
Leasing payments cover only the value a truck loses during your contract period. You also pay a finance charge called the money factor along with applicable taxes. Most agreements run about thirty-six months with yearly mileage caps attached to them.
Buying Builds Equity Over Several Years
A loan payment repays the full vehicle price plus interest over the chosen term. Once the balance reaches zero, you own a valuable asset with no further bills. Midsize pickups tend to hold resale value well, which strengthens this ownership advantage.
Hidden Charges Worth Checking Before Signing
Both options carry fees that rarely appear in advertised payment numbers. Reviewing them early prevents unpleasant surprises at the dealership desk later on.
- Acquisition fees often get added when a rental contract begins.
- Excess mileage penalties apply once yearly allowances are fully exceeded.
- Disposition charges may appear when returning the truck at term end.
- Loan origination costs sometimes increase the total amount you finance.
- Extended warranties raise ownership expenses unless you politely decline them.
Matching Each Option to Your Habits
You’re driving routine matters as much as the payment amount shown on paper. Finance managers at Space City Toyota can print both quotes side by side for easier review. Daily commuters covering long highway distances may find ownership more practical overall.
- Choose leasing when you prefer a fresh model every few years.
- Favour buying if heavy towing or custom upgrades fit your plans.
- Compare insurance quotes since lenders require fuller coverage on leased trucks.
| Payment size | Generally lower | Generally higher |
| End of term | Return or buy out | You keep the truck |
| Mileage rules | Yearly caps apply | No limits |
| Customization | Restricted | Allowed freely |
| Long term value | No equity | Builds equity |
Neither path wins for every household because priorities differ widely between buyers. Weigh flexibility against long-term savings before committing to either choice.
Answers to Common Shopper Questions
- Can I buy my truck when the leasing contract ends?Most agreements include a buyout price listed clearly within your original paperwork.
- Does a larger down payment lower my leasing bill?It lowers each bill slightly, yet that cash disappears if the truck gets totalled.
- Are auto loan rates higher today than in previous years?Rates remain above pandemic-era lows, so comparing several lenders still pays off.
Picking Your Path
Smaller bills suit shoppers who enjoy switching to newer models on a regular schedule. Ownership rewards patient buyers who keep their pickup long after the loan disappears. Fees plus mileage caps can quietly shift the math, so read every line carefully. Request two written quotes, then compare total spending across the full period rather than one month. The smartest decision blends today’s budget with tomorrow’s plans for that truck.